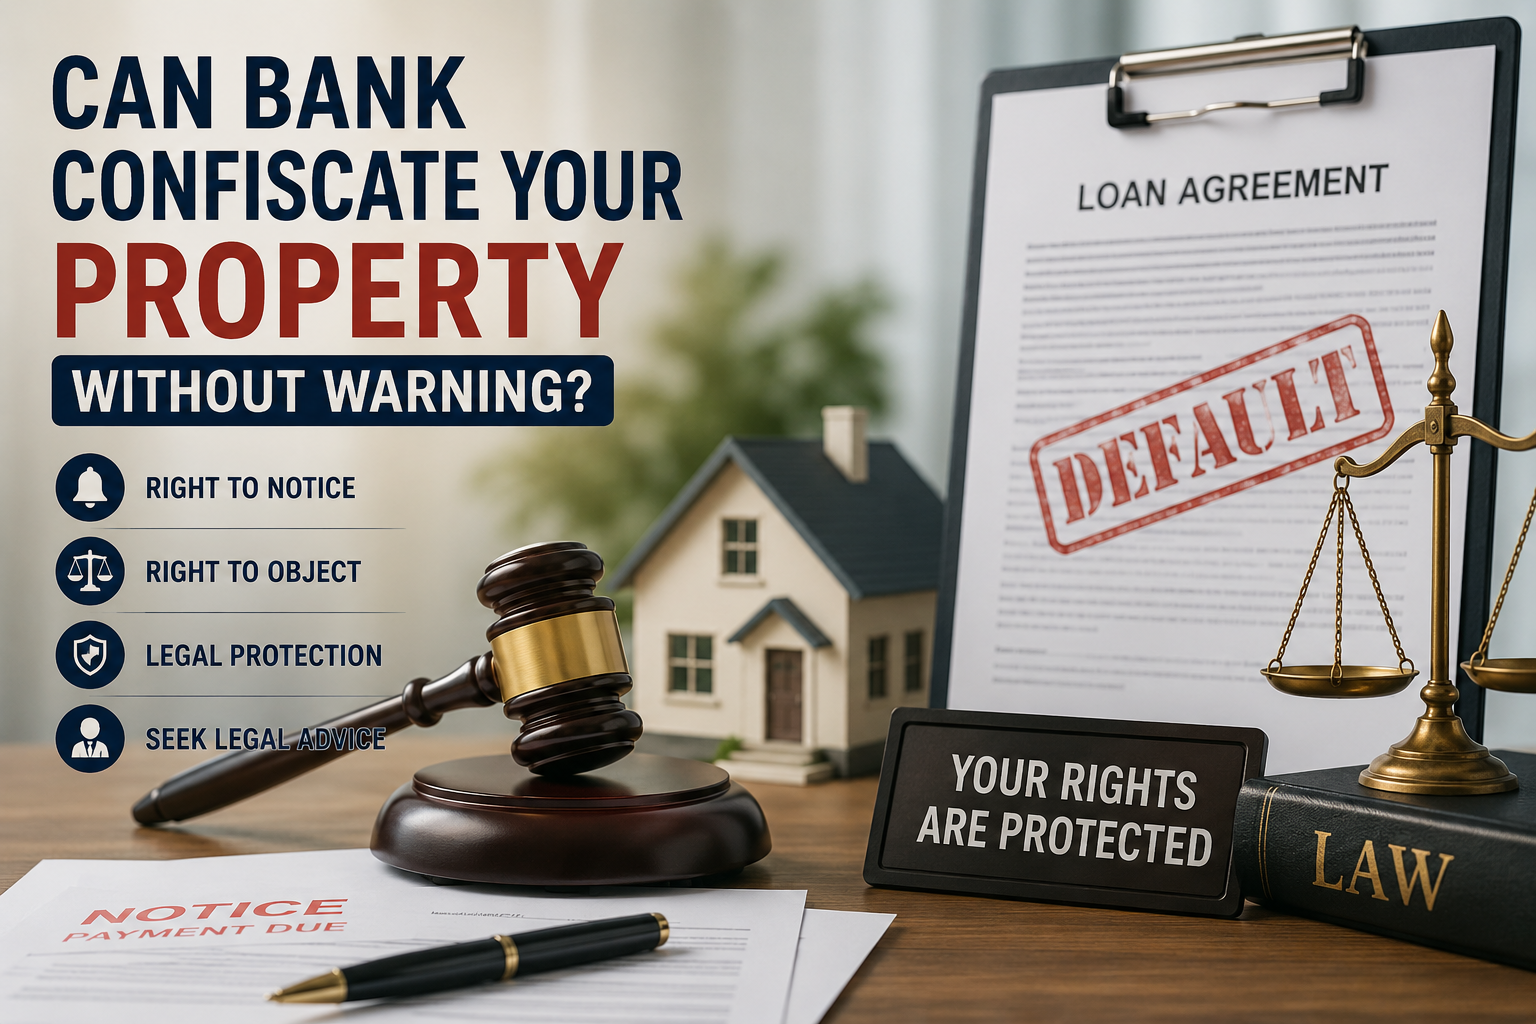
There are occasions when borrowers face financial problems and it becomes tough to repay the loans on time. A lot of individuals are afraid that if you don’t pay back the loan on time, the bank can come and take your property away without warning. Legally, banks and financial organisations have been empowered to recover overdue dues, but these powers are subject to regulations and processes laid out. Borrowers also enjoy important legal rights, which need to be upheld during the entire process of debt recovery. Awareness of such rights ensures that the borrower acts responsibly, seeks legal advice when necessary, and avoids unnecessary worries. In case you have availed yourself of a secured loan, it is essential that you know how legal proceedings operate in respect of property confiscation.
Is It Legal for the Bank to Confiscate My Property without Warning?
Generally speaking, in most cases the bank cannot take possession of your property that has been secured without undertaking legal proceedings in accordance with the existing laws. Normally, banks should give the borrower adequate notice and allow him/her to repay his/her dues or lodge any objections as may be provided by law before taking possession of his/her property.
Legal proceedings in the event of the recovery of secured loans like mortgage, home loans or loans against commercial property is a well-organized legal process. Details will vary depending on the type of loan, the existing banking laws, and the cause for default.
Having knowledge of the process of recovery
Several defaults in making payments can lead to an account of a borrower being labeled as Non-Performing Asset (NPA) according to the norms of banking industry. Simply because an asset is categorized as such does not mean that it is going to be taken over immediately.
Generally, the first step in the process of recovery begins with writing a letter to the borrower detailing how much money is owed and making demand within the prescribed time period. Generally, this process will follow established protocols and timetables.
Borrowers have a right to be noticed
One of the most important rights for borrowers is the ability to be properly notified before any major recovery action is taken. The notifications tell debtors of the debt owed, what the lender proposes to do about it and how long they have to cure the default.
Getting a notification also provides a chance to analyse the lender’s claims, verify the outstanding amount, discover any anomalies, and seek legal assistance if required. Never disregard such letters, since swift action may assist in resolving the situation before further legal procedures are commenced.
Right to object
Borrowers are not helpless in recovery processes. The borrower may have an opportunity to object or make representations if the recovery action is believed to be erroneous, excessive or not in compliance with legal standards before the lender goes further.
It could be conflicts on the computation of dues, classification of loan accounts, valuation of secured assets, procedural compliance, for instance. It is advisable to take proper legal recourse at the earliest to address these concerns and to safeguard the interests of the borrower.
Can Borrowers Challenge The Bank’s Action?
Yes, If the borrower thinks that the bank has not followed the appropriate legal procedure he may have legal remedies. Based on the facts of the case, they may seek the relevant judicial forum including the Debt Recovery Tribunal (DRT) to contest some of the recovery actions.
The tribunal determines whether the lender has met with any applicable legal requirements before taking possession or before beginning any recovery measures. Each case is judged on its individual facts thus it is vital to get legal advice before starting legal actions.
The Value of Prompt Legal Advice
Many borrowers wait until the recovery process is well underway before seeking legal counsel. Nevertheless, the early legal direction can often provide a clearer view of the available options and obligations.
The lawyer in Chennai can analyze the loan agreement, notices, payment history and all correspondence in order to determine if the collection activity was legal. Early legal engagement can also assist debtors to consider settlement choices, restructuring prospects or proper legal remedies if applicable.
Conclusion
Banks have legal tools for recovering overdue loans, but their powers are not boundless. Most cannot confiscate a borrower’s property without completing the right legal process and providing the required notices. Borrowers shall be entitled to information on recovery processes, have the right to file objections when provided for by law, and to take legal action if they believe that the lender has not complied with applicable laws. The awareness about such rights is going to assist the borrower in making well-informed decisions and reacting in a responsible manner to the issue of recovery. It is important to seek professional legal help immediately in order to ensure that your rights are safeguarded.